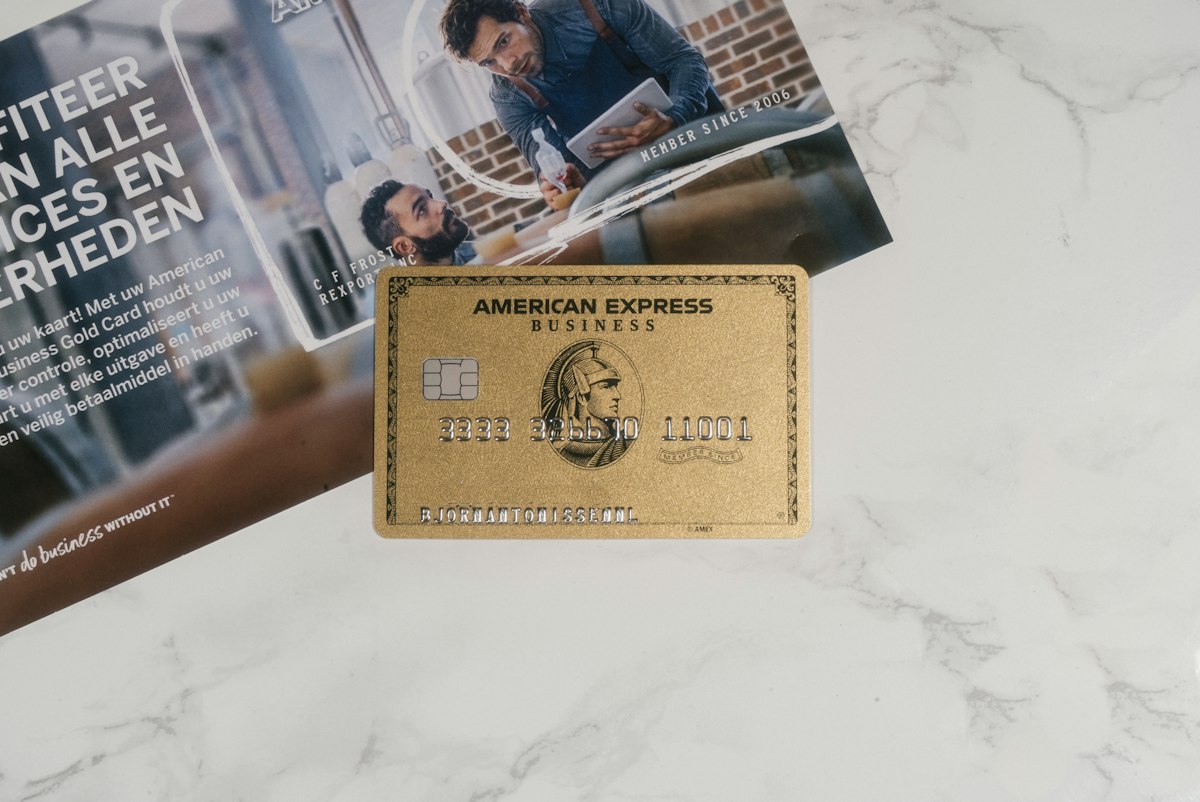
American Express Pre-Approval: How to Check Your Eligibility Risk-Free
Applying for a new credit card often feels like a gamble. You submit your personal information, cross your fingers, and hope the lender does not hand you a rejection letter alongside a permanent ding on your credit report. If you have your eye on a card from American Express, you do not have to fly blind.
American Express provides a pre-approval process that lets you see which cards you are likely to qualify for before you formally apply. This approach gives you clear insight into your standing without taking an immediate toll on your credit score.
Related posts
Mastering Your Union Bank Credit Card Application: Requirements and Success Tips
Choosing to start a Union Bank credit card apply process is a strategic move for anyone looking to...
Read more →
Maximizing Rewards with an Amex Credit Card: A Practical Selection Strategy
Selecting an Amex credit card often presents a classic financial trade-off: higher annual fees in exchange for premium...
Read more →Optimizing Enterprise Spend with the Amex Corporate Card Program
Managing a growing workforce requires more than just a standard business credit card; it demands a robust financial...
Read more →
Optimizing Corporate Spend: Strategic Evaluation of the American Express Corporate Card
Managing business expenditures across growing teams presents a persistent challenge for finance departments. Outdated reimbursement processes, unauthorized employee...
Read more →Understanding how Amex pre-approval works helps you make smarter financial decisions. Below, we break down the exact mechanics of the pre-screen process, the key differences between soft and hard credit inquiries, and practical strategies to improve your chances of getting approved.
Key Takeaways
- Zero Initial Credit Impact: Checking for pre-approval uses a soft credit check, which does not lower your credit score.
- No-Surprise Applications: Amex features an "Apply with Confidence" feature that lets you know if you are approved before accepting the card and triggering a hard pull.
- Credit Score Thresholds: Most Amex cards require good to excellent credit, typically starting around a 670 FICO score, though premium cards lean higher.
- Targeted Offers: Pre-approval often reveals specific welcome bonuses tailored to your credit profile.
Soft Pull vs. Hard Pull: How Amex Protects Your Score
The primary advantage of checking your pre-approval status is the type of credit inquiry performed. When you fill out the initial pre-qualification form on the American Express website, the issuer runs a soft credit inquiry. A soft pull allows Amex to review your credit file without placing an inquiry mark on your report. Lenders viewing your credit later will not see this soft check, and your score remains untouched.
In recent years, American Express streamlined this experience even further with their "Apply with Confidence" feature. When you submit a full application after checking your pre-approval, Amex determines whether you qualify before finalizing the approval. If you are approved and choose to accept the offer, only then will a hard inquiry be placed on your credit report. If you are declined, or if you decide not to accept the card, no hard pull is recorded.
Minimum Credit Requirements and Key Factors
While American Express does not publish hard minimum credit score rules for every product, patterns among approved applicants reveal clear benchmarks. Understanding where your profile stands helps set realistic expectations.
For entry-level cash back cards like the Blue Cash Everyday, a credit score of 670 or higher generally puts you in a competitive position. Higher-end rewards products—such as the American Express Gold Card or Platinum Card—typically demand scores in the 700 to 750+ range alongside a healthy income stream.
Beyond your credit score, American Express evaluates several specific factors during pre-screening:
- Payment History: A clean record free of recent late payments or collections.
- Credit Utilization: Keeping your total credit card balances well below 30% of your available limits.
- Income and Debt-to-Income Ratio: Sufficient income to cover prospective credit limits and existing obligations.
- Existing Amex Relationship: Current cardholders often see more tailored pre-approved offers based on their internal account history.
How to Check Your Amex Pre-Approval Offers
Checking your pre-screened offers takes only a few minutes online. Following a systematic approach ensures you retrieve accurate results without triggering unnecessary credit inquiries.
1. Head to the Official Pre-Screen Portal
Navigate directly to the American Express pre-qualification page on their official website. Avoid third-party aggregators if you want direct, real-time results straight from the issuer's internal engine.
2. Submit Your Basic Details
You will be asked to input basic personal details, including your full name, home address, income, and the last four digits of your Social Security Number. This information is used strictly to match your identity with your credit file for a soft pull.
3. Review Your Matched Cards
Once submitted, the system displays cards you pre-qualify for alongside prospective welcome bonuses and interest rates. Take time to evaluate annual fees, rewards structures, and terms before deciding which card aligns with your spending habits.
What to Do If You Are Not Pre-Approved
Failing to get pre-approved is not a permanent setback. It simply indicates that your current credit profile does not match Amex's active risk algorithms. Instead of applying anyway and risking a rejection, focus on strengthening your credit profile first.
Start by lowering your revolving balances to reduce your credit utilization ratio. Check your credit reports for any errors or outdated negative marks, and dispute discrepancies directly with the major credit bureaus. Additionally, avoid opening multiple new credit accounts in a short period, as frequent hard inquiries can signal financial distress to lenders.
Frequently Asked Questions
Does checking Amex pre-approval hurt my credit score?
No. Checking for pre-approval involves a soft credit check, which has no effect on your credit score. A hard inquiry only occurs if you accept an approved card offer.
Is pre-approval a guaranteed card approval?
While pre-approval indicates a very high probability of formal approval, it is not a 100% guarantee. Your full application must still undergo final verification, including income confirmation and recent changes to your credit file.
What credit score is needed for an Amex Gold Card?
Most successful applicants for the American Express Gold Card have a credit score of 700 or higher. A strong payment history and low credit utilization significantly increase your odds.
How often can I check for American Express pre-approval offers?
You can check for pre-approval offers whenever your financial situation changes or every few months. Because soft inquiries do not impact your credit score, checking periodically will not damage your standing.
Conclusion
Checking for American Express pre-approval is one of the safest ways to explore new credit options without risking damage to your credit score. By taking advantage of soft inquiries and Amex's conditional approval process, you can select the right rewards or cash back card with clear expectations. Review your credit profile today, check your pre-approved offers, and choose the card that best fits your financial goals.