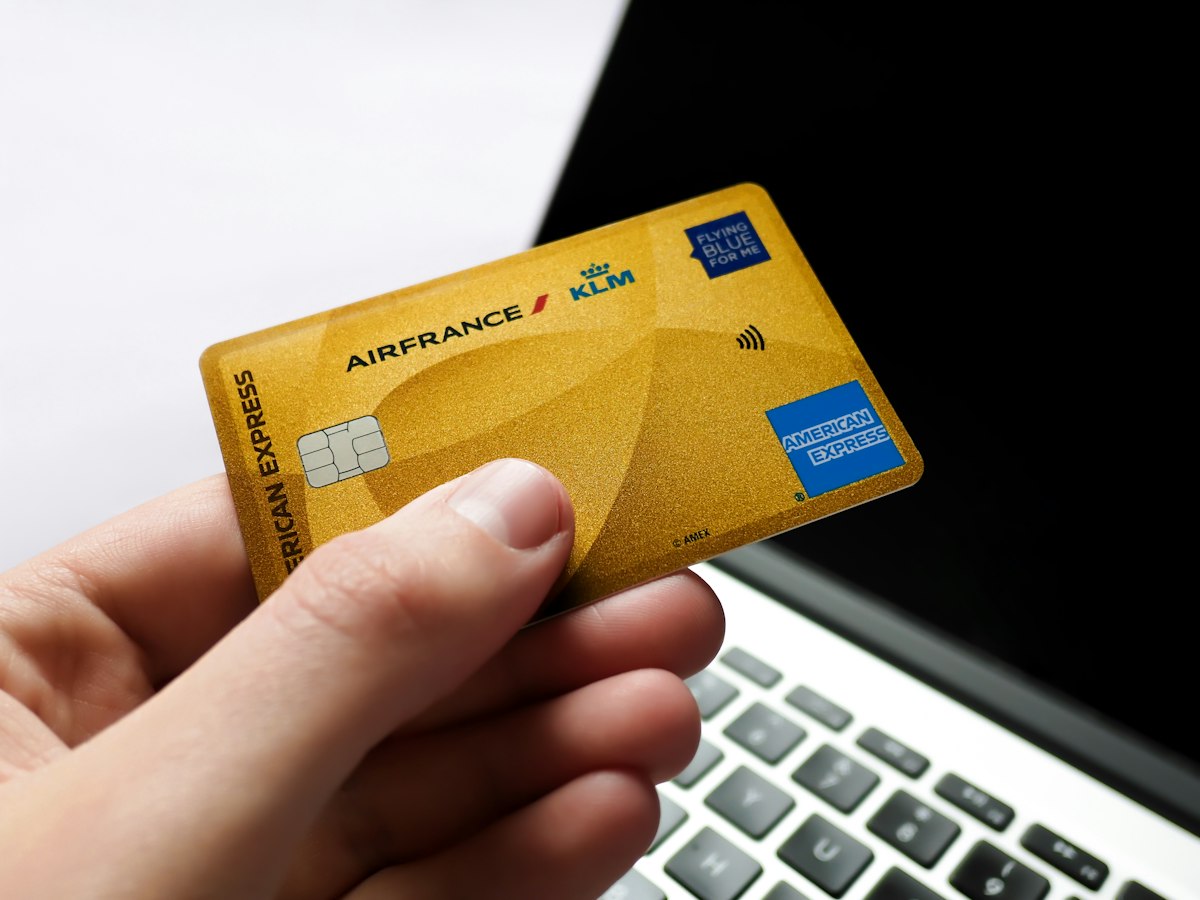
Understanding the Gold Card: A Strategic Choice for Enhanced Benefits
The phrase "gold card" often conjures images of exclusivity, elevated status, and a step above the ordinary. It's a term that carries a certain weight, suggesting premium benefits and a refined financial experience. But what does carrying a gold card truly mean in today's diverse credit landscape?
For many, a gold card represents a significant upgrade from a standard credit offering. It’s typically positioned in the middle tier of premium cards, sitting comfortably above basic options but often below the ultra-exclusive platinum or black cards. This positioning means it aims to strike a balance: offering substantial perks without the highest annual fees or the most stringent eligibility requirements.
Related posts
Mastering Your Union Bank Credit Card Application: Requirements and Success Tips
Choosing to start a Union Bank credit card apply process is a strategic move for anyone looking to...
Read more →
Maximizing Rewards with an Amex Credit Card: A Practical Selection Strategy
Selecting an Amex credit card often presents a classic financial trade-off: higher annual fees in exchange for premium...
Read more →Optimizing Enterprise Spend with the Amex Corporate Card Program
Managing a growing workforce requires more than just a standard business credit card; it demands a robust financial...
Read more →
Optimizing Corporate Spend: Strategic Evaluation of the American Express Corporate Card
Managing business expenditures across growing teams presents a persistent challenge for finance departments. Outdated reimbursement processes, unauthorized employee...
Read more →However, the label "gold" isn't universally defined. Different issuers interpret it in various ways, leading to a spectrum of offerings under the same banner. Understanding the nuances—from rewards structures and travel protections to annual fees and approval criteria—is key to determining if a gold card aligns with your spending habits and financial goals.
This article cuts through the marketing gloss to examine what a gold card genuinely offers. We’ll explore the common advantages, the considerations for eligibility, and how to assess if this particular tier of credit card is a smart addition to your financial toolkit.
Key takeaways
- Gold cards typically offer enhanced rewards, better travel benefits, and more robust purchase protections compared to standard cards.
- Expect annual fees, which necessitate a careful evaluation of whether the benefits outweigh the cost for your spending patterns.
- Eligibility often requires a good to excellent credit score and a stable income, reflecting the card's premium nature.
- The term "gold card" varies significantly between issuers; always review specific terms and conditions closely.
What Exactly Is a Gold Card? Defining the Premium Tier
At its core, a gold card is a type of credit card designed to offer more than just a means to make purchases. It's a product that bundles an array of benefits, services, and often, higher credit limits, aiming to attract consumers with strong credit profiles and higher spending potential. It signals a certain level of financial responsibility and often, a desire for more rewarding financial tools.
Beyond the Shine: Core Characteristics
While the specific features vary, several characteristics commonly define a gold card. You'll typically find more generous rewards programs, whether that's accelerated points on specific spending categories like dining or groceries, or higher cashback rates. Many gold cards also come with an array of insurance coverages, particularly for travel and purchases, which can offer genuine peace of mind.
The Spectrum of Gold: Not All Are Equal
It's important to recognize that the term "gold card" is not standardized across the industry. An American Express Gold Card, for instance, is a charge card known for its strong dining and grocery rewards, while a Visa or Mastercard branded as "Gold" by a bank might simply be a slightly enhanced version of their standard offering, perhaps with a higher credit limit and a few basic perks. Always look beyond the color and examine the actual terms and benefits.
The Perks and Privileges: What You Get with Gold
The primary appeal of a gold card lies in its suite of benefits. These are designed to add value beyond the simple transaction, often enhancing travel, offering security for purchases, and providing exclusive access.
Enhanced Rewards Programs
One of the most compelling reasons to consider a gold card is its rewards structure. Many offer bonus points or cashback on categories where consumers spend most, such as restaurants, supermarkets, or gas. These accelerated earning rates can quickly accumulate substantial rewards, which can then be redeemed for travel, merchandise, statement credits, or gift cards.
Travel Benefits and Protections
For those who travel frequently, gold cards can be particularly appealing. Common travel benefits include trip cancellation/interruption insurance, baggage delay insurance, car rental loss and damage waivers, and sometimes even a complimentary concierge service. While full airport lounge access is more common with platinum-tier cards, some gold cards may offer limited access or credits for travel-related expenses.
Purchase Protections
Beyond travel, gold cards often extend protections to your everyday purchases. This can include extended warranty coverage, which adds time to the manufacturer's warranty, purchase protection against damage or theft for a certain period after purchase, and even return protection if a merchant won't accept a return. These features can save cardholders money and hassle in unexpected situations.
Exclusive Access and Experiences
Some gold cards provide access to exclusive events, presale tickets, or special offers with partner merchants. While not a primary driver for most, these perks can occasionally offer unique experiences or savings that add to the card's overall value proposition.
Is a Gold Card Right for You? Weighing the Investment
Deciding if a gold card is a suitable choice involves more than just admiring its benefits. It requires a careful assessment of its costs, your financial habits, and your overall credit standing.
Understanding the Annual Fee
Most gold cards come with an annual fee. This fee covers the cost of the enhanced benefits and services the issuer provides. For the card to be a worthwhile investment, the value you derive from its rewards, protections, and perks should consistently exceed this annual charge. If you don't utilize the benefits, the fee can quickly erode any value gained.
Eligibility Requirements: What Issuers Look For
Because gold cards offer more, issuers typically require applicants to have a strong credit history. This usually means a good to excellent credit score (often 670+ FICO), a stable income, and a low debt-to-income ratio. They want to see evidence of responsible credit management and the capacity to handle a higher credit limit.
Matching Your Spending Habits to Benefits
The true value of a gold card often hinges on how well its reward categories align with your spending. If a card offers 4x points on dining and groceries, but you rarely eat out and buy most of your food from discount stores, you might not maximize its potential. Conversely, for someone who frequently dines out and travels, the accelerated rewards can be incredibly lucrative.
Comparing Gold to Other Tiers
Before committing, consider how a gold card stacks up against both standard and higher-tier cards. A no-annual-fee cashback card might be better if your spending is low or highly varied. If you're a luxury traveler or a very high spender, a platinum or black card, despite its higher fee, might offer superior benefits like extensive lounge access or dedicated personal services that justify the cost.
Applying for a Gold Card: What to Expect
If you've assessed your needs and a gold card seems like the right fit, the application process is straightforward but requires some preparation.
Preparing Your Application
Before applying, review your credit report for any inaccuracies and understand your current credit score. Gather information about your income, employment history, and monthly housing payments. Being prepared ensures a smooth application and helps you understand your likelihood of approval.
The Approval Process
Once you submit your application, the issuer will typically review your credit history, income, and other financial details. You might receive an instant decision, or it could take a few business days. If approved, your card will be mailed to you, along with the cardholder agreement detailing all terms and conditions.
Maximizing Your Card's Value from Day One
Upon approval, activate your card and familiarize yourself with its benefits. Many gold cards offer a substantial welcome bonus for meeting a certain spending threshold within the first few months. Strategically planning your initial purchases to meet this requirement can provide a significant boost to your rewards balance right away.
FAQ
What is the typical credit score needed for a gold card?
While specific requirements vary by issuer and card, most gold cards require a credit score in the "good" to "excellent" range, generally considered to be 670 or higher on the FICO scale. A strong payment history and responsible credit use are also important factors.
Are gold cards always better than standard credit cards?
Not necessarily for everyone. Gold cards offer more benefits and higher rewards, but they almost always come with an annual fee. For individuals who don't spend enough to outweigh the fee with rewards or who won't utilize the premium benefits, a no-annual-fee standard card might be a more financially sensible option.
Can a gold card help improve my credit score?
Yes, using any credit card responsibly, including a gold card, can help improve your credit score. This involves making on-time payments, keeping your credit utilization low, and not applying for too much new credit at once. Higher credit limits often associated with gold cards can also help lower your utilization ratio, provided you don't overspend.
How do I know if the annual fee is worth it?
To determine if an annual fee is worth it, calculate the monetary value of the rewards you expect to earn and the benefits you plan to use (e.g., travel credits, insurance savings). If this value consistently exceeds the annual fee, then the card is likely a good fit for you. Be realistic about your spending and benefit utilization.
What's the difference between a gold card and a platinum card?
Platinum cards generally sit a tier above gold cards. They typically offer more extensive and luxurious benefits, such as broader airport lounge access, higher travel credits, more comprehensive insurance coverages, and dedicated personal services. Consequently, platinum cards usually come with higher annual fees and more stringent eligibility criteria than gold cards.
Conclusion
A gold card is more than just a shiny piece of plastic; it's a financial instrument designed to offer enhanced value through superior rewards, protections, and services. The decision to acquire one should be a strategic one, rooted in a clear understanding of its costs, its benefits, and how well it integrates with your personal spending and travel habits. By carefully evaluating your own financial profile and the specific terms of a gold card, you can determine if it's the right choice to elevate your credit experience and provide tangible advantages.