Instant Credit Card: How to Get Approved and Start Spending Today
Waiting two weeks for a physical piece of plastic to arrive in the mail feels like a relic of a different era. When you have an immediate expense, a time-sensitive balance transfer, or a travel booking that cannot wait, you need access to funds right now. The traditional banking model of application, manual review, and postal delivery is increasingly being replaced by systems that offer an immediate decision and, in many cases, immediate access to your new credit line.
An instant credit card typically refers to one of two things: a card that provides a decision within seconds or a card that provides a virtual account number the moment you are approved. While many lenders promise speed, the reality of what happens after you click "submit" can vary significantly between issuers. Understanding the nuances of how these systems work can save you from unnecessary credit inquiries and help you get the spending power you need without the standard waiting period.
Related posts
Maximizing the Benefits of Zero Interest Credit Cards
Watching high-interest debt accumulate is a frustrating experience that can feel like running on a treadmill that keeps...
Read more →
Smart Credit Cards to Build Credit and Improve Your Financial Standing
Staring at a low credit score or a completely blank credit history feels like being locked out of...
Read more →
Finding the Best Balance Transfer Credit Cards to Eliminate High Interest Debt
Are you tired of watching your credit card balance barely budge despite making consistent monthly payments? High interest...
Read more →
Maximize Savings with Strategic Credit Card Balance Transfer Offers
High-interest debt often feels like running on a treadmill that keeps getting faster. You make your monthly payments,...
Read more →This discussion covers the mechanics of instant approval, the rise of virtual card numbers, and the specific types of cards that are most likely to offer immediate utility. We will also look at the eligibility requirements that lenders use to make these split-second decisions and how you can position your credit profile to increase your chances of a "yes." Whether you are looking for a retail card for a specific purchase or a general-purpose card for everyday use, the speed of modern fintech is on your side.
By the end of this article, you will know exactly which features to look for and how to manage a new account that exists entirely in your smartphone before the physical card even hits the production line. We will move past the marketing jargon to see what is actually possible in the current lending environment.
Key takeaways
- Instant approval is different from instant use: Many cards give a quick decision, but only a subset provide a virtual card number for immediate spending.
- Eligibility is data-driven: Automated underwriting systems rely on your current credit score and income verification to make decisions in seconds.
- Retailers lead the pack: Store-branded cards are often the fastest to offer immediate credit for use at their specific locations or websites.
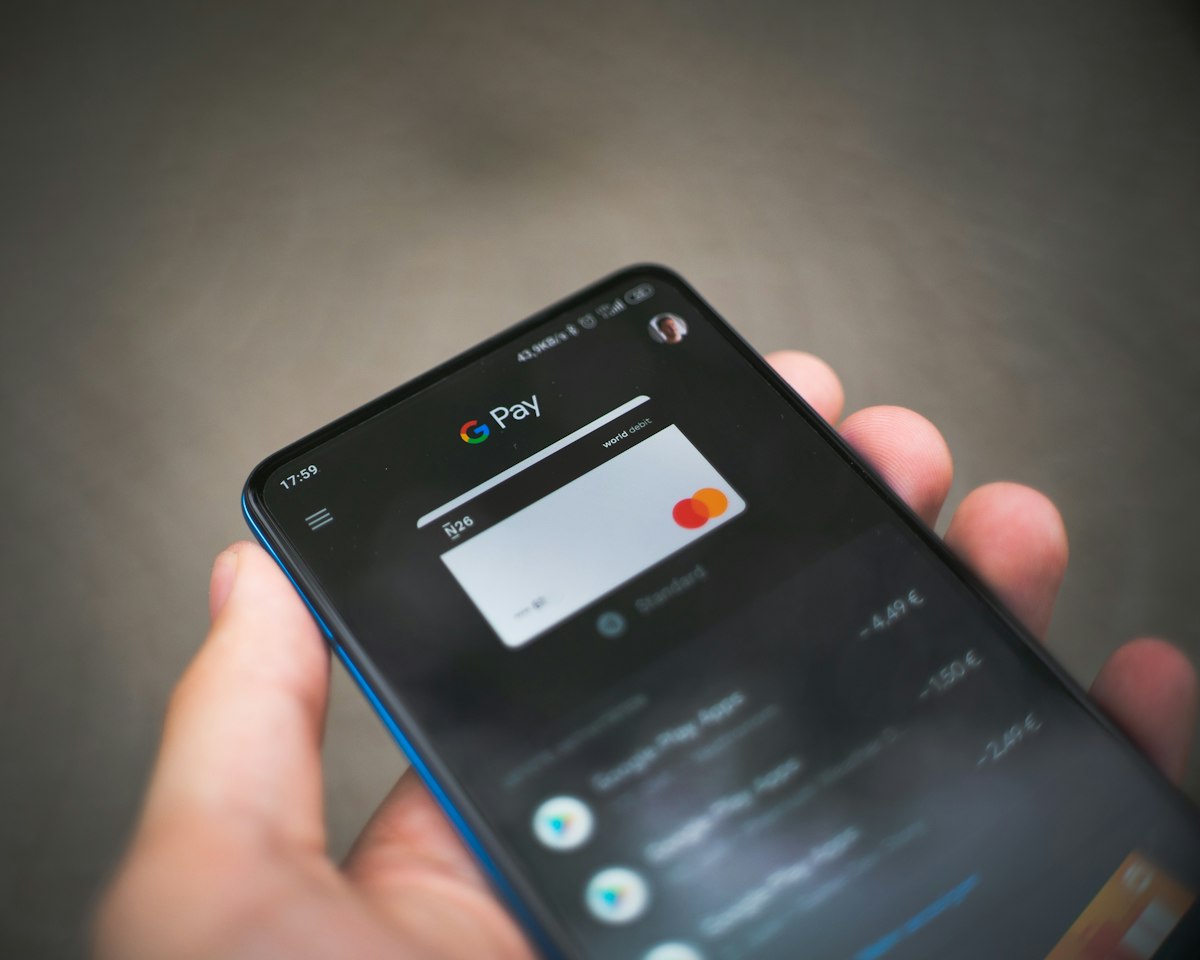
- Digital wallets are essential: To use an instant card at a physical register, you will likely need to add the virtual details to Apple Pay, Google Pay, or a similar service.
The Reality of Instant Approval
When a lender advertises an instant credit card, they are usually highlighting their automated underwriting system. In the past, a human loan officer had to review your application, check your references, and manually pull your credit report. Today, sophisticated algorithms do this in the time it takes for a webpage to refresh. These systems scan your credit history, debt-to-income ratio, and public records to determine your risk level instantly.
However, an "instant approval" does not always mean you can go out and buy a television five minutes later. For many traditional banks, the approval is just the first step. You might still have to wait for the physical card to arrive to access the CVV code and expiration date. If your goal is immediate spending, you must look specifically for issuers that offer instant credit card numbers or virtual cards upon approval.
Instant Approval vs. Instant Access
It is important to distinguish between these two terms. Instant approval means the bank has decided to lend to you. Instant access means the bank provides your account details immediately via their mobile app or a secure web portal. This allows you to add the card to a digital wallet or use it for online shopping. Without instant access, an instant approval is simply a promise that a card is on its way.
How Virtual Cards Bridge the Gap
The rise of the virtual card has been a game-changer for those seeking an instant credit card. A virtual card is essentially a digital version of your credit card with its own unique 16-digit number, expiry date, and security code. Some issuers provide a temporary virtual number that works until your physical card is activated, while others provide the permanent details immediately.
Lenders like American Express, Capital One, and Apple (via the Apple Card) have become leaders in this space. For example, once approved for an Apple Card, it is integrated into your iPhone's Wallet app within seconds. You can use it at any merchant that accepts contactless payments. This is the gold standard for the modern consumer who values speed and convenience over traditional banking hurdles.
Types of Instant Credit Cards Available
Not all cards are created equal when it comes to speed. Depending on your credit score and your specific needs, you might find that one category of card is easier to obtain quickly than others.
Store and Retailer Cards
Retailers were among the first to offer instant credit. Think of the last time you were at a department store and the cashier offered you a discount if you opened a card on the spot. These cards are designed for immediate use at that specific retailer. Because store cards often have lower credit limit requirements and higher interest rates, the approval process is frequently more lenient and faster than general-purpose cards.
Fintech and Neobank Offerings
Modern financial technology companies (fintechs) are built on the premise of speed. These companies often use alternative data to verify your identity and creditworthiness. They are more likely to offer a digital-first experience where the physical card is almost an afterthought. If you are comfortable managing your entire financial life through an app, these are often the best candidates for a truly instant experience.
Premium Travel and Cash Back Cards
While more traditional, some major banks have updated their systems to compete. Some premium travel cards will give you your card number immediately so you can book a flight or hotel and start earning rewards right away. However, these usually require an excellent credit score, as the bank is taking a higher risk by allowing immediate large-scale spending.
Eligibility and Requirements for Instant Approval
What does it take to get that instant "yes"? While every lender has its own secret sauce for underwriting, several factors are almost always at play. If your application triggers a red flag, it will be kicked to a manual review process, which can take anywhere from a few days to two weeks.
- A Clean Credit Report: If there are freezes on your credit report, the automated system cannot access your data, and your application will be delayed. Always unfreeze your credit before applying.
- Verifiable Income: You will need to state your annual gross income. Some systems can verify this through third-party databases or by asking you to link your bank account via a service like Plaid.
- Stable Residency: Frequent moves or inconsistencies in your address can sometimes trigger identity verification checks that slow down the process.
- Existing Relationship: If you already have a checking account or another loan with a bank, they are much more likely to approve you instantly because they already have a history of your financial behavior.
The Application Process: Step-by-Step
To ensure the fastest possible experience, you should have all your information ready before you start the application. Any hesitation or need to look up data can cause the session to time out, potentially leading to a pending status rather than an instant decision.
First, gather your Social Security number, total annual income, and monthly housing payment. Second, ensure your mobile device is updated, as many instant cards require you to use the bank's app for identity verification, which might include taking a photo of your driver's license or a selfie to match your ID. Finally, once you submit, do not refresh the page. Let the algorithm do its work.
If you receive a message saying your application is "under review," do not panic. This doesn't mean a denial; it just means the system found something that requires a human eye. You can often call the bank's reconsideration line to provide more context and potentially speed up that manual review.
Risks and Considerations
The convenience of an instant credit card comes with specific responsibilities. Because the process is so fast, it can be easy to overlook the terms and conditions. Interest rates on instant-approval cards, particularly store cards, can be significantly higher than the market average. If you do not plan to pay off the balance in full every month, the cost of that convenience could be high.
Furthermore, applying for multiple instant cards in a short period can damage your credit score. Each application typically triggers a "hard inquiry," which can shave a few points off your score. If you are denied for one card, it is usually better to find out why rather than immediately applying for another.
Security in the Digital World
Using a virtual or instant card requires a proactive approach to security. Since you are accessing your account details through an app or website, ensuring your device is secure is paramount. Use biometrics like FaceID or fingerprint scanning, and never share your virtual card details over unencrypted channels like email or text. Most instant cards offer the ability to "freeze" the card instantly from the app if you notice suspicious activity, which is a powerful tool for protecting your credit line.
Frequently Asked Questions
Can I get an instant credit card with bad credit?
While it is more difficult, it is not impossible. Some store cards and "secured" credit cards offer instant or near-instant decisions for those with lower scores. However, you may not get instant access to the funds, as secured cards require a deposit first.
How soon can I use an instant credit card?
If the issuer provides a virtual card number or allows you to add the card to a digital wallet, you can use it within minutes of approval. If they do not offer these features, you will have to wait for the physical card to arrive in 5 to 10 business days.
Does an instant credit card have a lower limit?
Not necessarily. Your credit limit is based on your creditworthiness and income, not the speed of the approval. However, some issuers might give you a smaller "temporary" limit that increases once you activate your physical card.
Can I use an instant card at an ATM?
Usually, no. Most instant-access features are restricted to online purchases or contactless payments via a digital wallet. Cash advances typically require the physical card and a PIN, which is sent separately for security reasons.
What happens if my application is not approved instantly?
If the system cannot make a decision, your application status will change to "pending." You will usually receive a letter or email within 7 to 10 days with a decision or a request for more information, such as proof of identity or income.
Conclusion
The era of waiting for credit is rapidly coming to an end. An instant credit card offers a level of flexibility and responsiveness that matches the pace of modern life. By choosing an issuer that provides virtual account numbers and ensuring your credit profile is ready for an automated check, you can move from application to purchase in a matter of minutes. However, always remember that the speed of the transaction does not change the fundamentals of debt. Use these tools wisely, pay attention to the interest rates, and enjoy the convenience of having your financial resources available exactly when you need them.